Canada’s digital economy is expanding, yet progress remains uneven. The country scored 0.67 in the OECD Digital Government Outlook 2026, trailing the OECD average of 0.70 and ranking 20th globally in digital competitiveness. While the sector now contributes nearly 10% of GDP and employs more than 2.4 million Canadians, this modest 0.01 improvement since 2023 signals a transitioning economy that’s growing but facing headwinds in government digital maturity and global positioning.
The stakes are considerable. Digitally enabled services already represented 13% of Canada’s exports in 2025, and projections suggest the digital economy could contribute nearly $250 billion annually to GDP by 2030. Yet achieving this target requires addressing persistent gaps in infrastructure, skills development, and policy coordination that have kept Canada from breaking into the top tier of digital nations.
For professionals and policymakers tracking this transition, the challenge is clear: translating economic potential into measurable advancement. Current federal targets, including 50/10 Mbps high-speed Internet connectivity for all Canadians, establish a baseline, but closing the competitiveness gap demands more than infrastructure alone. The data reveals an economy in motion, with workforce expansion and export diversification underway, but one that must accelerate its pace to match international peers and capture the full value of digital transformation.
What Changed: Recent Shifts in Canada’s Digital Economy Transition
Canada’s digital economy transition entered 2026 with sobering metrics and modest momentum. The OECD Digital Government Outlook 2026 assigned Canada a score of 0.67, falling short of the 0.70 average among member nations and reflecting a marginal 0.01 improvement since 2023. This incremental gain underscores the challenge facing policymakers and industry leaders: narrowing a 0.03-point gap requires accelerated effort, not gradual adjustment.
The country’s standing in global digital competitiveness tells a similar story. Canada ranked 20th globally a position that signals competence but not leadership among advanced economies. This ranking carries economic consequences, particularly as peer nations pull ahead in areas driving innovation, productivity, and resilience.
Yet the fundamentals reveal capacity worth building on. Canada’s digital economy now contributes nearly 10% of GDP and employs more than 2.4 million people, demonstrating scale that reaches across sectors and regions. Digitally enabled services represented 13% of the country’s exports in 2025, a figure that highlights growing international relevance even as it exposes dependence on continued advancement.
The transition challenge is clear: converting this established foundation into competitive advantage. Meeting the projected $250 billion annual GDP contribution by 2030 requires moving from modest gains to substantial shifts in infrastructure deployment, skills development, and adoption across traditional industries. The following developments illustrate where progress is occurring and where urgency remains.
Key Developments Driving the Transition
1. Digital Service Exports Reach 13% of Total Exports
Digitally enabled services reaching 13% of exports in 2025 marks a significant milestone in Canada’s economic transition, signaling a structural shift toward knowledge-intensive, high-value activities that depend less on physical resources and more on digital infrastructure and talent. This figure represents not just incremental growth but a fundamental change in how Canada competes globally, moving from traditional goods-heavy exports toward services that scale rapidly, require minimal physical distribution, and generate higher margins per employee.
The composition of these digital service exports reveals where Canada is building competitive advantage:
- Information and communications technology services, including cloud computing, software development, and managed IT services
- Professional services delivered digitally, such as consulting, legal advisory, and financial analysis for international clients
- Creative and digital media, encompassing content creation, design services, and digital entertainment products
- Education technology and online learning platforms serving international markets
- Research and development services leveraging Canada’s university partnerships and innovation capacity
This export performance creates immediate workforce implications. Digital service delivery demands workers with advanced technical skills, cross-cultural communication abilities, and comfort operating in distributed teams across time zones. Companies exporting these services compete for talent in a global market, driving up wage expectations and forcing Canadian employers to invest more heavily in training and retention. The 2.4 million workers currently employed in the digital economy will need continuous upskilling to maintain competitiveness as service offerings evolve and client expectations rise.
Economic diversification benefits extend beyond headline numbers. Provinces historically dependent on resource extraction or manufacturing gain pathways to participate in the digital economy through specialized service niches. A consulting firm in Halifax or a software development shop in Saskatoon can serve clients in New York or London as easily as Toronto-based competitors, provided connectivity and talent are adequate. This geographic flexibility matters for national resilience, reducing vulnerability to commodity price swings and regional downturns.
2. Progress Toward $250 Billion GDP Target by 2030
Canada’s digital economy stands at an inflection point. Current contribution hovers at nearly 10% of GDP, while the 2030 target of $250 billion annual contribution demands substantially faster growth. Closing this gap requires both the acceleration of existing momentum and the removal of structural barriers that currently limit expansion.
The arithmetic is straightforward but challenging. Reaching $250 billion by 2030 means compounding growth well above historical rates, particularly in sectors already demonstrating strength. Digitally enabled services, which represented 13% of exports in 2025, offer one clear pathway. Expanding this export footprint demands competitive pricing, reliable connectivity across all regions, and workforce capacity that scales with opportunity.
Investment remains a critical constraint. While Canada employs 2.4 million workers in the digital economy, capital flows into infrastructure, research, and commercialization lag behind peer nations. The 20th global ranking in digital competitiveness reflects this gap. Bridging it requires coordinated public and private investment in broadband expansion, particularly to meet the 50/10 Mbps connectivity target, alongside funding for technology development and skills training.
Sector-specific patterns reveal where growth must concentrate. Software development, data analytics, cybersecurity, and cloud services represent high-value areas with export potential. Manufacturing and resource sectors integrating digital technologies also contribute, though productivity gains in these traditional industries unfold more slowly than pure technology ventures.
The 0.01 score improvement since 2023 in the OECD Digital Government Outlook signals progress, but the pace must quicken. Achieving the 2030 target depends on deliberate focus, not incremental drift.
3. Digital Infrastructure and Connectivity Expansion
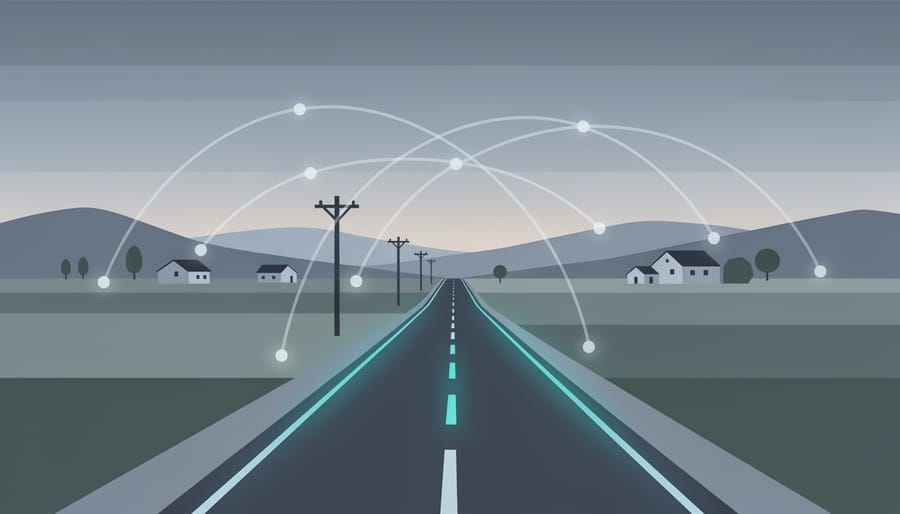
Canada’s path toward universal high-speed Internet connectivity remains central to enabling widespread digital economy participation. The federal government’s 50/10 Mbps minimum target sets the baseline for what communities need to access cloud services, participate in remote work, and engage in digital commerce. While progress continues, significant coverage gaps persist in rural and remote regions where economics make infrastructure deployment challenging.
The connectivity divide directly impacts how different regions capitalize on digital economy opportunities. Urban centres benefit from competitive fibre networks and 5G deployment, supporting density-dependent innovations like smart cities infrastructure and advanced manufacturing. Meanwhile, communities without reliable high-speed access struggle to attract remote workers, support distributed teams, or enable local businesses to compete in digital markets. This gap affects not just individual users but entire regional economies’ ability to participate in Canada’s transition.
Small and medium enterprises face particular constraints when connectivity falls short. Cloud-based business tools, video collaboration platforms, and digital payment systems all assume consistent high-speed access. An SME in a rural area without adequate bandwidth can’t effectively adopt the same productivity tools as urban competitors, creating structural disadvantages that compound over time.
Emerging tech hubs outside major metros depend on connectivity infrastructure to attract talent and enable collaboration. Remote research facilities, satellite offices for technology companies, and innovation centres in smaller cities all require robust Internet access as their operational foundation. As Canada works toward its $250 billion GDP contribution target by 2030, closing connectivity gaps becomes an economic imperative rather than just an infrastructure goal.
4. Workforce and Digital Skills Development Momentum
Canada’s digital economy employs over 2.4 million people, yet closing the competency gap remains one of the most pressing challenges in the transition. The sector demands a continuous supply of workers equipped with advanced technical skills, data literacy, and the ability to adapt as technologies evolve. Current workforce development efforts span post-secondary institutions, industry-led training programs, and employer-driven upskilling initiatives, but the pace of digital transformation often outstrips the rate at which new talent enters the market.
Educational institutions have expanded computer science, data analytics, and cybersecurity programs, while industry partnerships bring real-world projects into classrooms and create pathways from graduation to employment. Bootcamps, micro-credentials, and apprenticeship models complement traditional degrees, targeting mid-career professionals seeking to reskill for digital roles. Employers increasingly invest in internal training to address niche skill shortages, recognizing that waiting for ready-made talent is no longer viable.
Despite this momentum, the skills gap persists. Demand for AI specialists, cloud architects, and cybersecurity experts exceeds supply, and many smaller enterprises lack the resources to compete for scarce talent. Sustaining workforce readiness will require coordinated efforts across government, education, and industry to align training with market needs and ensure all regions benefit from capacity-building investments.
Why This Transition Matters Now
Canada’s standing at 20th globally in digital competitiveness represents more than a numerical ranking. It signals a widening gap in the capacity to attract talent, scale innovation, and capture value from the digital transformation reshaping every sector of the economy. The 0.03-point deficit below the OECD average of 0.70 may seem modest, but it reflects systemic challenges in infrastructure deployment, regulatory adaptation, and coordination across federal, provincial, and private actors. Nations ahead of Canada are pulling further away, investing aggressively in broadband networks, research commercialization pathways, and education systems that embed digital literacy from early childhood through professional retraining.
Economic resilience depends on diversification beyond resource extraction and traditional manufacturing. With digitally enabled services already representing 13% of exports, the transition offers a path to insulate Canada from commodity price volatility and expand competitive advantages in business services, software development, and knowledge-intensive industries. Yet realizing that potential requires closing skills gaps across the 2.4 million workers already in the digital economy and preparing millions more for roles that do not yet exist. Education institutions, employers, and governments must coordinate to make your digital career accessible regardless of geography or prior credentials, ensuring rural communities and underrepresented groups share in the transition’s benefits rather than being left behind.
What to Watch: Critical Factors Shaping the Path Forward
Several indicators will signal whether Canada’s digital economy transition gains momentum or stalls. Watch the OECD Digital Government Outlook score closely; closing the 0.03-point gap to the average and moving beyond 0.67 requires sustained investment in digital infrastructure, skills development, and regulatory frameworks that support innovation. The path to the $250 billion GDP target by 2030 demands accelerated growth beyond the current 10% contribution, which means tracking not just aggregate numbers but sector-specific performance in AI, cybersecurity, fintech, and digitally enabled services.
Export figures offer another critical barometer. If digitally enabled services rise beyond 13% of total exports, it indicates growing competitiveness in global markets. Conversely, stagnation suggests structural barriers that need immediate attention. Digital competitiveness rankings will reveal whether Canada is keeping pace with peer nations or slipping further from the top 15.
How long will it take Canada to reach the OECD average for digital government?
At the current pace of 0.01 improvement since 2023, reaching the 0.70 average would take three years if the average remains static. However, accelerated investment in infrastructure and workforce development could shorten this timeline.
What are the biggest investment needs for the digital economy transition?
Priorities include expanding high-speed connectivity to meet the 50/10 Mbps target universally, developing digital skills across 2.4 million workers, and supporting SME adoption of emerging technologies. Public-private partnerships will be essential to fund these areas.
Can successful international models apply in Canada?
Yes, though adaptation is necessary. Proven approaches from other nations can scale to Canada when adjusted for geography, population distribution, and existing infrastructure.
Public-private partnerships represent a leverage point worth monitoring. Organizations bridging research, education, and industry can accelerate capacity development in ways government or business cannot achieve alone. The effectiveness of these collaborations will determine how quickly Canada builds the workforce, infrastructure, and innovation ecosystems needed to move from 20th place toward the top tier of digitally competitive nations.